
Payroll is the largest single expense for most service-based businesses, often consuming 50–70% of total revenue. Yet many SMB owners treat payroll cost management as a back-office function rather than a strategic lever. The result: bloated headcount, runaway overtime, hidden tax liabilities, and margins that quietly erode quarter after quarter. This guide shows you exactly how to take control — without firing your best people or destroying morale.
Table of Contents
- What Payroll Cost Management Really Means
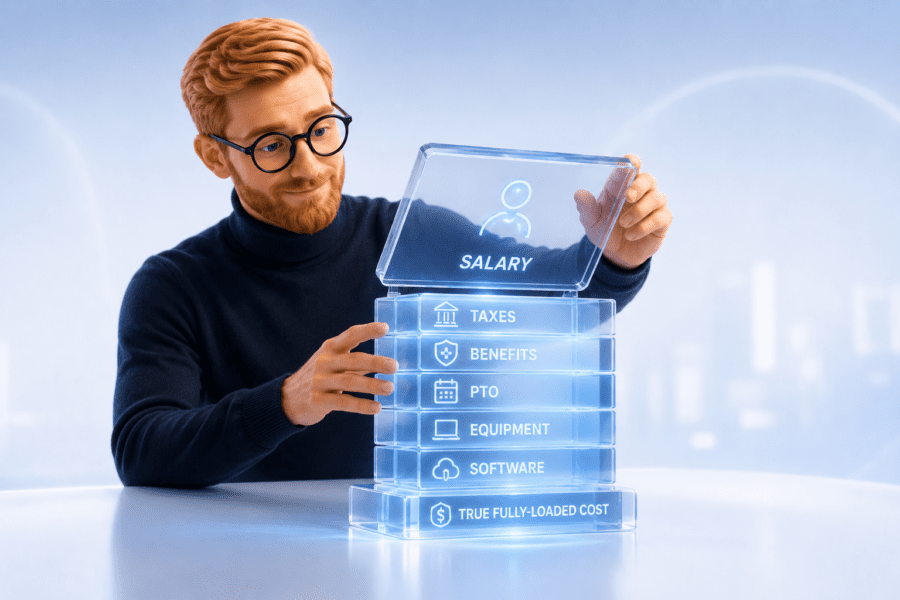
- The True Cost of an Employee (It’s Not the Salary)
- 7 Payroll KPIs Every Owner Must Track
- 9 Proven Strategies to Control Payroll Costs
- How to Eliminate Hidden Overtime Leaks
- Case Study: A $4M Agency That Cut Payroll 18%
- Payroll Cost Audit Checklist
- FAQ
What Payroll Cost Management Really Means
Payroll cost management is the disciplined process of measuring, optimizing, and forecasting all employee-related expenses — base pay, taxes, benefits, overtime, contractors, and the productivity each dollar generates. It’s not about paying people less. It’s about making sure every payroll dollar produces measurable output.
Most owners look at payroll as a fixed monthly bill. CFOs look at it as a portfolio of investments. Each role, team, and shift either generates margin or drags it down — and the numbers tell you which is which.
Key Takeaways
| Insight | Why It Matters |
|---|---|
| True employee cost is 1.25–1.4x base salary | Most owners underestimate fully-loaded labor cost by 25–40% |
| Revenue per employee is the #1 productivity metric | Healthy SMBs target $200K–$500K depending on industry |
| Overtime above 5% of payroll signals a structural problem | Usually understaffing, bad scheduling, or unclear priorities |
| Headcount freezes work better than layoffs | Natural attrition cuts costs without morale damage |
| Tracking labor cost as % of revenue beats absolute dollars | Lets you scale with confidence and spot drift early |
The True Cost of an Employee (It’s Not the Salary)
When a business owner says “I pay her $80,000,” they’re usually wrong by tens of thousands of dollars. The real, fully-loaded cost includes everything below — and ignoring it is one of the most expensive mistakes in profit margin analysis.
| Cost Component | Typical Range | $80K Salary Example |
|---|---|---|
| Base salary | 100% | $80,000 |
| Employer payroll taxes (FICA, FUTA, SUTA) | 7.65–10% | $6,500 |
| Health insurance | 5–12% | $7,200 |
| 401(k) match | 3–6% | $3,200 |
| Workers’ comp & disability | 1–4% | $1,600 |
| Paid time off (treat as productivity loss) | 4–8% | $5,000 |
| Equipment, software, workspace | 3–7% | $4,000 |
| Fully-loaded cost | 125–140% | $107,500 |
That $80,000 hire actually costs you $107,500. Multiply across 20 employees and the gap between what you think you’re spending and reality is over $500,000 per year.
7 Payroll KPIs Every Owner Must Track
Without metrics, payroll cost management is just guessing. These are the seven numbers I review every month with clients.
1. Labor Cost as % of Revenue
The single most important payroll metric. Healthy benchmarks by industry:
| Industry | Target Labor % |
|---|---|
| Professional services / agencies | 40–55% |
| SaaS | 35–50% |
| Restaurants | 28–35% |
| Construction | 25–35% |
| Retail | 15–22% |
| Manufacturing | 20–30% |
2. Revenue per Employee (RPE)
Annualized revenue divided by full-time equivalent (FTE) headcount. Track quarterly. A declining RPE while revenue grows means you’re hiring faster than you’re producing.
3. Gross Profit per Employee
Even better than RPE because it accounts for direct costs. A consulting firm doing $2M revenue with $1.4M gross profit and 10 employees has $140K gross profit per head — a strong number.
4. Overtime as % of Total Payroll
Above 5% is a yellow flag. Above 8% is a red flag. Either you’re understaffed or your scheduling is broken.
5. Payroll Tax Effective Rate
Your blended employer tax rate. Should track stable; sudden jumps usually mean a SUTA experience-rating change you missed.
6. Benefits Cost per Employee
Benchmark against your industry. If you’re 20%+ above peers, renegotiate your health plan or shift contribution structure.
7. Time-to-Productivity for New Hires
How many months until a new hire produces output that exceeds their fully-loaded cost? Above 9 months is expensive — fix onboarding before hiring more.
9 Proven Strategies to Control Payroll Costs
1. Implement a True Headcount Approval Process
Every backfill or new hire requires written justification: the role’s revenue contribution, payback period, and what work it eliminates. Most “we need more people” requests evaporate when owners ask for the math.
2. Convert Fixed Roles to Variable Where Possible
Fractional CFOs, contract designers, freelance developers, and agencies let you scale capacity up and down with demand. This is exactly the model behind our EBITDA improvement work — variable cost structures protect margins in downturns.
3. Use Headcount Freezes Before Layoffs
Average annual employee turnover in the US is 17%. A 9-month freeze on a 30-person team naturally reduces headcount by 3–4 people without a single termination. Cheaper, less disruptive, and better for morale than layoffs.
4. Audit Overtime Monthly
Pull an OT report every month by employee, manager, and reason code. Repeat OT in the same department means a structural fix is needed, not more hours.
5. Restructure Bonus Plans Around Profitability, Not Revenue
Revenue-based bonuses incentivize discounting and bloated deals. Tie bonuses to gross margin, EBITDA, or cash collected — and watch behavior change within one quarter.
6. Negotiate Health Insurance Annually
Benefits brokers earn commission on your premiums; they’re not always motivated to find savings. Get three independent quotes every year. 8–15% savings is common.
7. Use a Compensation Band System
Define salary bands by role and level. Ad-hoc raises and counter-offers create payroll drift that’s nearly impossible to unwind. Bands force discipline and make compensation defensible.
8. Outsource Non-Core Functions
Bookkeeping, payroll processing, IT, customer support tier 1, and admin work are usually 30–50% cheaper through specialized providers than full-time hires — once you account for fully-loaded cost.
9. Monitor Span of Control
If managers oversee fewer than 6 direct reports, you likely have too many layers. Each unnecessary management layer adds 10–15% to payroll without producing output.
How to Eliminate Hidden Overtime Leaks
Overtime is the most controllable line item in payroll, yet it’s where most SMBs lose the most money. A typical breakdown of why overtime balloons:
| Root Cause | % of OT Cases | Fix |
|---|---|---|
| Last-minute project changes | 32% | Stricter scope/change control |
| Understaffing in one shift/team | 28% | Hire one strategic FTE; OT savings pay it back in 6 months |
| Misclassified exempt vs. non-exempt | 15% | Audit job descriptions against FLSA tests |
| “Heroes” who self-extend hours | 14% | Manager approval required above 5 OT hours/week |
| Bad scheduling software/process | 11% | Implement scheduling tool with predictive forecasting |
One client — a 22-person customer support operation — was burning $94,000/year in overtime. Two structural changes (one new hire and a manager-approval rule above 5 OT hours weekly) eliminated 78% of it within 90 days. Net savings after the new hire: $32,000 in year one, $73,000 in year two.
Case Study: A $4M Agency That Cut Payroll 18%
A digital marketing agency with $4M revenue and 28 employees came to us with payroll at 62% of revenue — well above the 50% target for their model. Margins were thin, owner take-home was minimal, and they couldn’t fund growth.
What we did over 90 days:
- Audited every role’s revenue contribution; identified 3 redundant positions and 2 underutilized seniors
- Implemented a 6-month headcount freeze (no backfills without C-level sign-off)
- Converted 2 senior roles to fractional contracts (saved ~$140K fully-loaded)
- Renegotiated health plan: 11% premium reduction
- Restructured account manager bonuses from billings to gross margin
- Capped overtime above 5 hours/week behind manager approval
Results after 6 months:
| Metric | Before | After | Change |
|---|---|---|---|
| Payroll % of revenue | 62% | 51% | -11 pts |
| Annual payroll spend | $2,480,000 | $2,040,000 | -$440K |
| Headcount (FTE) | 28 | 23 | -5 |
| Revenue per employee | $143K | $174K | +22% |
| EBITDA margin | 4% | 15% | +11 pts |
No layoffs were required — natural attrition handled the headcount reduction. The freed cash funded a sales hire that drove revenue growth in the following two quarters.
The Cash Flow Impact of Payroll Decisions
Payroll runs on a fixed cycle whether revenue comes in or not. That’s why payroll cost management is inseparable from cash flow forecasting. Three rules:
- Always carry 2–3 payroll cycles in cash reserves. If you have a 2-week pay period and $200K per cycle, keep $400K–$600K liquid at all times.
- Stagger pay periods if possible. Bi-weekly creates two 3-payroll months per year that crush cash flow. Plan for them.
- Forecast payroll changes 60–90 days out. A new hire’s true cash impact starts before day one (recruiter fees, equipment, training).
Building Payroll Controls That Catch Problems Early
Strong financial controls apply to payroll as much as cash. The four non-negotiables:
- Segregation of duties — the person who adds employees should not be the one who approves payroll runs.
- Quarterly ghost-employee audit — match payroll registers to active employee lists and HR records.
- Monthly variance review — actual payroll vs. budget, with explanations for any variance over 3%.
- Annual classification audit — confirm every contractor genuinely meets the IRS 20-factor test. Misclassification penalties are brutal.
Payroll Cost Audit Checklist
Run through this once per quarter. Each “no” is money on the table.
- Do you know your fully-loaded cost per employee (not just salary)?
- Is labor cost as % of revenue tracked monthly with industry benchmarks?
- Is revenue per employee trending up or flat (not down)?
- Is overtime under 5% of total payroll?
- Do you have written approval workflow for every backfill and new hire?
- Are bonus plans tied to profit metrics, not just revenue?
- Have you re-quoted health insurance in the last 12 months?
- Do you have defined salary bands by role and level?
- Are non-core functions (bookkeeping, IT, admin) evaluated for outsourcing?
- Do you carry 2+ payroll cycles in cash reserves?
- Is your span of control (reports per manager) at least 6:1?
- Have you classified all contractors against the IRS 20-factor test in the last year?
Ready to Take Control of Your Biggest Expense?
If payroll is eating your margins and you don’t have the systems to fix it, that’s exactly what fractional CFO work is built for. We help SMBs benchmark, restructure, and optimize labor costs without sacrificing the people who matter. Book a free consultation and we’ll review your payroll metrics together — no obligation, just clarity.
You may also want to read our guides on working capital optimization and profit margin analysis to see how payroll decisions ripple through every other financial metric.
Frequently Asked Questions
What percentage of revenue should payroll be for a small business?
It depends entirely on industry. Service businesses (agencies, consultancies, SaaS) typically run 40–55%. Restaurants run 28–35%. Retail runs 15–22%. The right benchmark for your business is your industry median plus or minus 5 points. Anything outside that range warrants investigation.
How do I reduce payroll costs without firing employees?
Start with a headcount freeze that uses natural attrition to reduce FTE count. Then renegotiate benefits, audit overtime, restructure bonuses around profit metrics, and convert non-core fixed roles to variable contracts. These five moves together typically reduce payroll cost by 8–15% within 12 months — without a single layoff.
What’s the difference between salary and fully-loaded employee cost?
Salary is what shows on the offer letter. Fully-loaded cost includes employer payroll taxes (~7.65%), health insurance, 401(k) match, workers’ comp, paid time off, equipment, software, and workspace. The multiplier is typically 1.25–1.4x base salary. An $80K hire usually costs $100K–$112K all-in.
Should I hire employees or use contractors?
Use contractors for project-based, specialized, or fluctuating-demand work. Use employees for core ongoing functions where you need consistency, control, and culture. The decision is rarely about cost alone — misclassifying employees as contractors creates serious tax exposure. Run any contractor through the IRS 20-factor test before signing.
How often should I review payroll costs?
Monthly at minimum. Pull labor cost as % of revenue, overtime %, revenue per employee, and headcount changes every month. Do a deeper quarterly review including span of control, compensation band drift, and benefits costs. Run a full annual audit covering classification, ghost employees, and benefits competitiveness.